How Traffic Violations Affect Car Insurance Rates
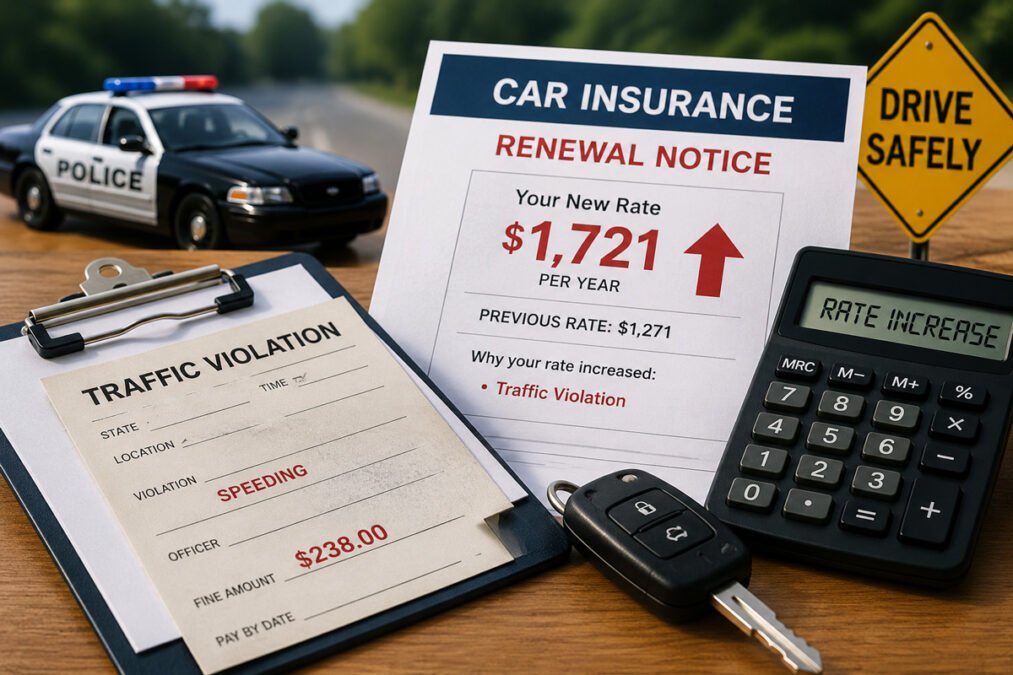
Traffic violations affect insurance rates because insurers use your driving record to estimate future risk. A ticket may not raise your premium immediately, but once it appears on your motor vehicle record, it can follow you into your next renewal.
Getting a ticket is expensive twice: first when you pay the fine, and later if your insurance premium increases. Most drivers know their rates can go up after a violation, but fewer understand when the increase happens, which violations hurt the most, or what options may limit the damage.
This guide explains how insurers treat traffic violations, how long the insurance impact can last, and what you can do after a ticket.
Do Traffic Violations Affect Insurance Rates?
Yes. Traffic violations can affect insurance rates when they appear on your motor vehicle record and your insurer reviews that record, usually at renewal. Minor tickets may cause a smaller increase, while serious violations such as reckless driving, DUI, hit and run, or at-fault accidents can lead to much higher premiums or even non-renewal.
| Question | Short Answer |
|---|---|
| When does insurance usually go up after a ticket? | At renewal, after the insurer checks your driving record |
| How long can a violation affect rates? | Often three to five years, depending on the violation, state, and insurer |
| Do all tickets affect insurance? | No. Parking tickets usually do not affect insurance because they are not moving violations |
| What violations hurt most? | DUI, reckless driving, hit and run, major speeding, driving without insurance, and at-fault accidents |
| What can help after a ticket? | Dismissal, a defensive driving course, quote shopping at renewal, or forgiveness programs |
How Insurance Companies Learn About Your Violations

Your insurer usually does not learn about a ticket on the day you receive it. A ticket generally becomes relevant to insurance after it results in a conviction and appears on your motor vehicle record.
Insurers may review the motor vehicle records of drivers listed on a policy, commonly when the policy renews, although they do not necessarily check every driver at every renewal. If a violation appears within the insurer’s lookback period, the company may consider it when calculating the new premium.
This explains why your rate may not increase immediately after a ticket. A violation received shortly before renewal could affect your next premium, while one received just after renewal might not be considered until a later review.
Important: An insurer may also check your driving record when you apply for a new policy, add a driver, change vehicles, or make certain coverage changes. Removing DMV points does not necessarily remove the underlying conviction from your record or prevent an insurance surcharge.
Even if the violation remains on your driving record, you may still have ways to limit its financial impact. Review these practical strategies for how to lower your car insurance through available discounts, policy adjustments, and comparison shopping.
How Much Does a Ticket Raise Your Rates?
The increase depends on three things: the severity of the violation, your insurer’s rating system, and your prior record. Minor violations such as a first low-range speeding ticket usually have less impact than serious violations such as reckless driving, DUI, or an at-fault accident.
General impact by violation type:
| Violation type | Typical rate impact |
|---|---|
| Minor speeding (1–14 mph over) | Moderate increase at renewal |
| Major speeding (15+ mph over) | Larger increase; may affect eligibility for preferred rates |
| Running a red light | Similar to moderate speeding |
| Reckless driving | Significant increase; some insurers non-renew |
| At-fault accident | Often larger than a single ticket; surcharge may apply |
| DUI / DWI | Severe increase; SR-22 filing required in most states |
A first minor violation on an otherwise clean record typically produces the smallest increase. The same violation on a record that already has a violation in the past three years produces a much larger one — insurers view pattern behavior differently than isolated incidents.
Which Violations Hurt Your Insurance the Most?
Not all violations are equal in an insurer’s eyes. Most companies use their own rating rules, but the pattern is usually similar: minor moving violations matter, serious violations matter much more, and non-moving violations often do not affect premiums.
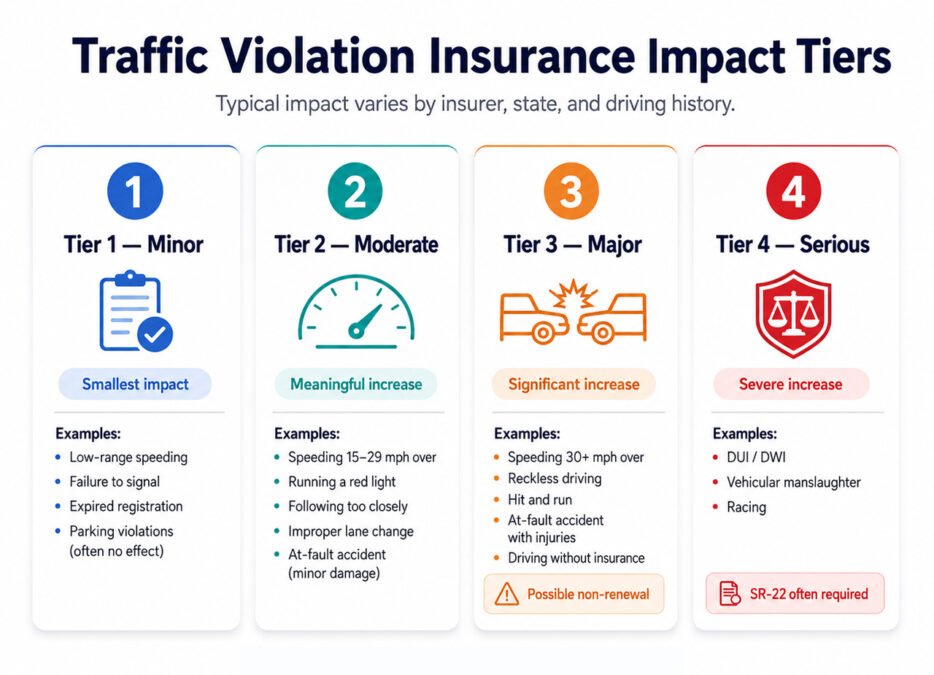
Tier 1 — Minor violations
These usually have the smallest insurance impact:
- Low-range speeding, such as under 15 mph over the limit
- Failure to signal
- Minor equipment violations
- Expired registration
- Parking violations, which often do not affect insurance at all
Tier 2 — Moderate violations
These can create a meaningful rate increase:
- Speeding 15–29 mph over the limit
- Running a red light
- Following too closely
- Improper lane change
- At-fault accident with minor damage
Tier 3 — Major violations
These can cause a significant increase and may affect eligibility with some insurers:
- Speeding 30+ mph over the limit
- Reckless driving
- Hit and run
- At-fault accident with injuries
- Driving without insurance
Tier 4 — Serious violations
These can create severe insurance consequences:
- DUI / DWI
- Vehicular manslaughter
- Racing
- Multiple serious violations within a short period
Where a violation lands depends partly on state law and partly on your insurer’s internal rating table. Two drivers with the same ticket can see different insurance outcomes if they use different companies.
How Long Does a Violation Affect Your Rates?
Many minor violations affect insurance rates for about three years, but the real answer depends on your state, insurer, and the type of violation. Serious violations such as DUI, reckless driving, or driving without insurance can affect rates for longer.
There are two timelines to understand:
| Timeline | What It Means |
|---|---|
| DMV record timeline | How long the violation remains on your official driving record |
| Insurance lookback window | How far back your insurer looks when pricing your policy |
Your insurer’s lookback window determines how much of your driving history is used for rating. Many insurers look back three years; some look back five years or more for serious violations. A ticket that is outside your insurer’s lookback window may stop affecting your premium even if it still appears on your driving record.
What this means in practice: a minor speeding ticket from three years and one month ago may no longer affect your rate with one insurer, while the same ticket from two years and eleven months ago may still count. Timing matters at renewal.
Because state rules vary, check your state DMV or motor vehicle agency if you need to know exactly how long a violation remains on your record.
What You Can Do After a Ticket
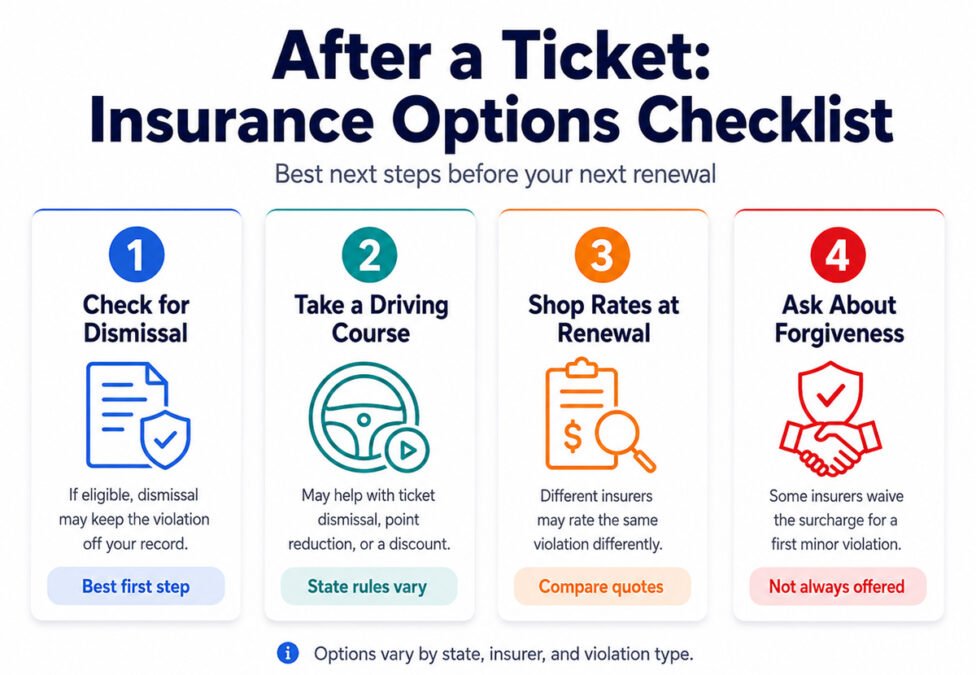
1. Check whether the ticket can be dismissed
In some states, completing a defensive driving course may allow an eligible ticket to be dismissed. If the ticket is dismissed before it becomes a conviction, it may never reach your insurer as a rated violation.
Eligibility varies by state and court. Dismissal is usually limited to minor moving violations, and many states limit how often you can use this option.
See how to get a speeding ticket dismissed for state-specific eligibility rules.
2. Complete a defensive driving course for the insurance discount
Even if ticket dismissal is not available, many insurers offer a discount for completing a state-approved defensive driving course. This usually does not erase the violation, but it may partially offset the increase.
See traffic school insurance discount: can it lower your rate? for how the discount works and what to expect.
3. Shop your rate at renewal
A violation that raises your premium sharply with one insurer may have a smaller impact with another. Each company weighs traffic violations differently. If your rate jumps at renewal, get quotes from at least two or three competitors before you renew.
Do not compare only the monthly price. Check deductibles, coverage limits, excluded drivers, fees, and whether the quote includes the same coverage you currently have.
4. Ask about accident forgiveness or violation forgiveness programs
Some insurers offer programs that waive the surcharge for a first accident or minor violation after a clean-driving period. These programs vary widely and may not apply if the violation is serious.
Check your policy documents or call your insurer directly. Forgiveness programs are not always advertised clearly.
How to Protect Your Rates Before a Violation Happens
The most effective approach is keeping your record clean in the first place. That means practicing defensive driving habits, understanding common enforcement areas, and avoiding the situations where violations are most likely.
Traffic violations often cluster around:
- Construction zones, where fines may be higher and enforcement may be more frequent
- School zones, where speed limits and right-of-way rules are enforced strictly
- Intersections, especially for red-light, stop-sign, and right-of-way violations
- Roads where the speed limit recently changed
- Highways where traffic speed makes it easy to drift above the limit
A few practical habits can reduce violation risk:
- Set your GPS speed alert to the posted limit if your navigation app supports it
- Give yourself extra time so you are not rushing to appointments
- Know the speed limits on roads you drive frequently, especially where they change
- Increase following distance so you are not forced into sudden braking or unsafe lane changes
- Avoid using your phone while driving, even briefly
For focused guidance on limit changes, speed creep, school and work zones, and pressure from faster traffic, follow these practical habits for avoiding speeding tickets.
Keeping a clean record for three or more years can help you qualify for better rates with many insurers. It also gives you more options when shopping for coverage.
Official Source to Check
Auto insurance is regulated at the state level, and rating rules vary by insurer and state. For general consumer guidance, the National Association of Insurance Commissioners lists driving record, claims history, vehicle type, location, and other factors as common auto insurance rating factors:
- NAIC Auto Insurance topic page: https://content.naic.org/insurance-topics/auto-insurance
For state-specific point rules, record retention, ticket dismissal, or SR-22 requirements, check your state DMV, motor vehicle agency, or state insurance department.
Frequently Asked Questions
Will my insurance go up if I get a ticket in another state?
Usually, yes. Out-of-state violations can appear on your home-state driving record, depending on state reporting rules and the type of violation. If the violation appears on your motor vehicle record, your insurer may see it at renewal.
Does a ticket affect my insurance immediately?
Usually not. Your insurer typically sees the ticket when it reviews your driving record, often at renewal. If your renewal is six months away, the rate increase may not appear until then.
Can I hide a ticket from my insurance company?
No. If a violation appears on your motor vehicle record, your insurer can see it when it checks that record. The practical way to prevent a ticket from affecting your insurance is to resolve it before conviction, such as through dismissal if your state or court allows it.
Does paying the fine immediately mean I am convicted?
In many states, paying a traffic ticket is treated as admitting guilt or pleading guilty. That can put the violation on your driving record. If you want to contest the ticket, seek dismissal, or ask about traffic school, check your options before paying.
What is an SR-22, and do I need one?
An SR-22 is a certificate of financial responsibility that an insurer files with the state to confirm that you carry required coverage. It is commonly required after serious violations such as DUI, driving without insurance, or repeated serious offenses. Requirements vary by state, and not all insurers offer SR-22 filing.
Will a defensive driving course remove points from my record?
It depends on your state. Some states allow point reduction through an approved defensive driving course, but point reduction is different from an insurance discount. Point reduction affects your DMV record. An insurance discount depends on your insurer’s rules.
Do parking tickets affect car insurance rates?
Parking tickets usually do not affect car insurance rates because they are not moving violations. However, unpaid parking tickets can create other problems with registration renewal, late fees, or collections depending on your state or city.
How long should I shop for new insurance after a ticket?
A good time to shop is when you receive your renewal notice after the violation appears on your record. Compare several quotes using the same coverage limits and deductibles. If the violation is serious, also confirm that the new insurer is willing to write the policy before canceling your current coverage.
What It Comes Down To
A traffic violation is a real cost, not just because of the fine, but because of the premium increase that can follow at renewal and last for years. The best response depends on your situation.
If dismissal is available, explore that before paying the fine. If dismissal is not available, a defensive driving course may still help with a discount or point reduction, depending on your state and insurer. If your rate has already increased, renewal is the right time to compare quotes.
The insurer that rates you highest after a violation may not be the most competitive option for your profile going forward.


